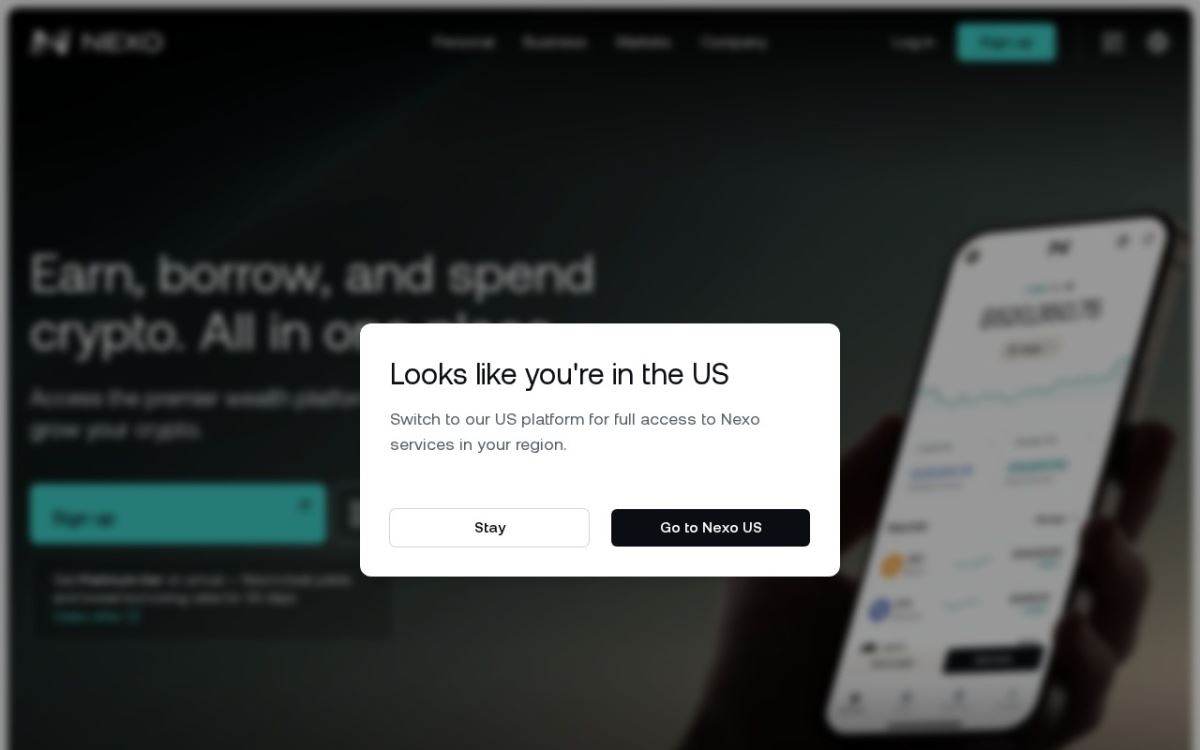
Nexo runs two separate platforms under one brand. Visitors from the United States who land on the international site get a pop-up offering to "switch to our US platform", and the US platform is a materially different product: custody sits with Bakkt, a publicly listed US company, the advertised yield ceiling is higher, and eight product lines that appear in the international menu do not appear in the US one.
That split is easy to miss, because almost every review of Nexo describes a single platform. If you are comparing it against wherever your digital assets currently sit, the version you can actually open decides what you are comparing.
The two menus, side by side
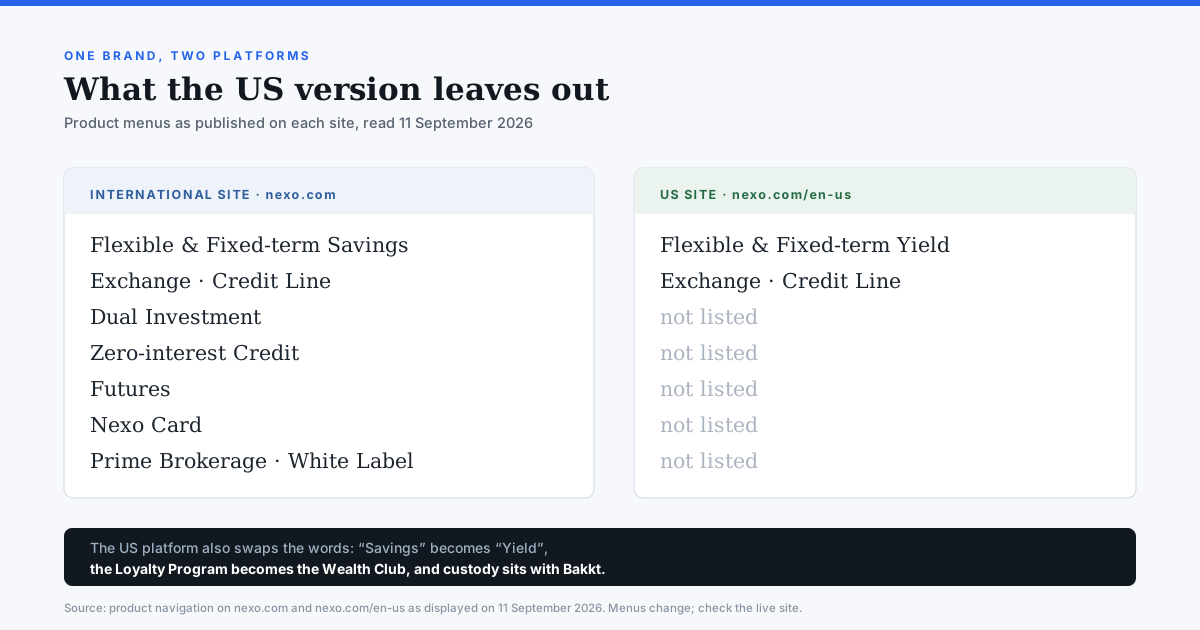
Taking each site's own product navigation at face value, the international site lists Flexible and Fixed-term Savings, Exchange, Credit Line, Dual Investment, Zero-interest Credit, Futures, the Nexo Card, Private Clients and a Loyalty Program, plus Prime Brokerage, White Label, Nexo Ventures and a Payment Gateway on the business side.
The US site lists a shorter set: Buy assets, Flexible Yield, Fixed-term Yield, Credit Line, Exchange, Private Clients, a Wealth Club, and Corporate Accounts.
So the following appear in the international menu and not in the US one: Dual Investment, Zero-interest Credit, Futures, the Nexo Card, Prime Brokerage, White Label, Nexo Ventures and the Payment Gateway. Two more are renamed rather than removed - "Savings" becomes "Yield", and the Loyalty Program becomes the Wealth Club.
A missing menu item is not proof a product is unavailable to every US client in every circumstance. It does mean Nexo is not offering it to US visitors on the page where it sells everything else, which is the practical answer for anyone deciding today.
The numbers are not the same either
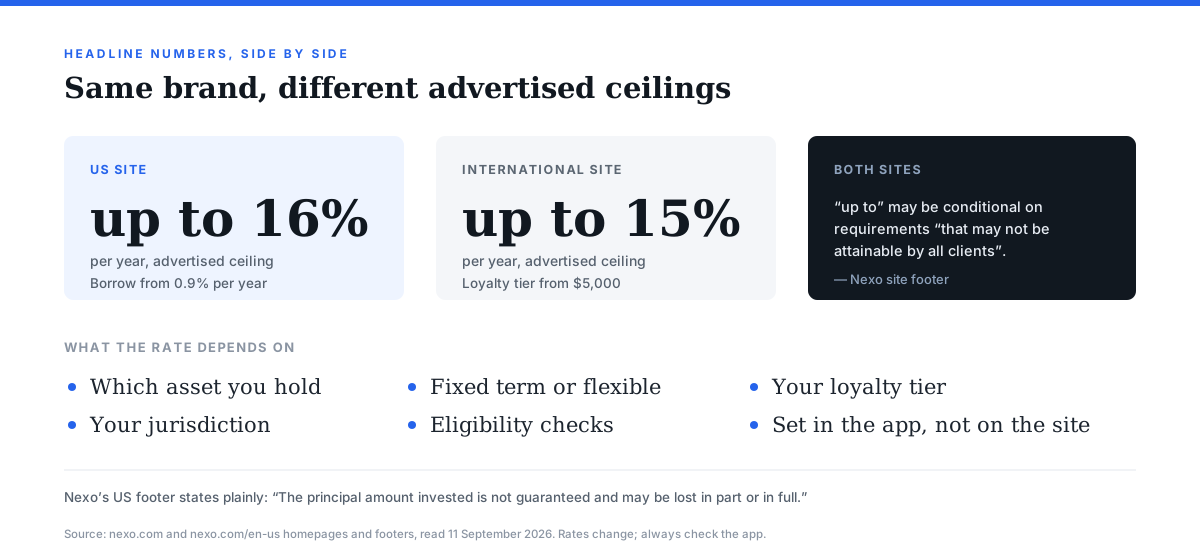
The international homepage advertises earning "up to 15% annually". The US homepage advertises "rates of up to 16% per year" and borrowing "from 0.9% per year" on a crypto-backed Credit Line. Both sites attach the same footnote to the phrase up to: reaching those thresholds "may be conditional on additional actions or fulfilment of certain criteria and requirements that may not be attainable by all clients".
Both sites also say the rate that applies to you is set in the app and varies by asset, term, tier and jurisdiction. No article can honestly quote you the number you will be shown, and any that does is guessing.
Who actually holds the assets
This is the structural difference that matters most, and it is the one buried furthest down the page. The US site states that assets are "held with Bakkt, a publicly listed U.S.-based digital asset platform purpose-built to support institutional risk management and compliance". The international site makes no equivalent third-party custody claim on its homepage; it leads instead with its own certifications - ISO 27001, 27017, 27018 and SOC 2 Type 2.
The US page cites "SOC 2 and SOC 3 audits". Both figures sets are worth reading as what they are: security and process audits describe how systems are run. They are not statements about solvency, and neither company treats them as such.
The scale figures each site publishes
- $7+ billion in assets under management - stated on both sites. The international footer dates this to Q2 2026 and says it is updated quarterly.
- $1.7+ billion loan book - US site only.
- $465+ billion in transaction volume and issued collateralised credit, and $1.5+ billion in interest paid to clients - US site only.
- 10+ million clients worldwide, present in 200+ jurisdictions, operating since 2018.
- Nexo Private for individuals and family offices with $100,000 or more in digital assets - both sites.
These are company-published figures. We have not seen them independently audited, and we are not presenting them as verified - only as what Nexo states about itself.
Funding an account, if you are in the US
The US platform lists ACH transfers and wire transfers as funding methods, with Nexo fees waived "for a limited time" at the time of writing. The international site instead offers named personal USD, EUR and GBP accounts, card payments including Apple Pay and Google Pay, and regional payment methods. If moving money in and out matters more to you than the yield headline - and for most businesses it does - that is the section to read first. For the ordinary, non-crypto side of moving business money around, our payments and banking reviews cover the tools most companies actually run on.
What both versions say about risk
Nexo's own US footer is more direct than most of the coverage written about it, and it is worth quoting rather than paraphrasing.
Digital asset prices are volatile and may fluctuate significantly. The principal amount invested is not guaranteed and may be lost in part or in full.
It goes on: "Borrowing against digital assets involves risk, including liquidation risk due to market volatility", and "No returns are guaranteed". That liquidation point is the one people underestimate. A crypto-backed credit line is a collateralised position - if the value of what you posted falls far enough, it can be closed out. That is the mechanism working as designed, not a malfunction.
Neither platform is a bank. Balances are not deposits and are not covered by FDIC in the US or FSCS in the UK.
What is not published
Three things we could not establish from public pages and will not guess at. The actual rate table - both sites push you to the app. Whether the US product set will widen - the menus state today's position and nothing about the future. Which entity holds what under the Bakkt arrangement beyond the single sentence quoted above; Nexo points to Bakkt's own disclosures for detail.
Common questions
Is Nexo available in the United States?
Yes, through a separate US platform at nexo.com/en-us, with custody held at Bakkt. US visitors to the international site are prompted to switch to it.
Is the US version the same product?
No. Eight product lines listed in the international menu are absent from the US menu, including the Nexo Card, Futures, Dual Investment and Zero-interest Credit. Savings products are renamed Yield, and the Loyalty Program is called the Wealth Club.
Which one advertises the higher rate?
The US site, at up to 16% per year versus up to 15% internationally. Both are ceilings with conditions attached, not standard rates.
Is Nexo a bank?
No. It is a digital asset platform. Balances are not bank deposits and carry no deposit insurance.
Does it serve companies?
Both sites list Corporate Accounts. The international site adds Prime Brokerage, White Label and a Payment Gateway, which the US menu does not show.
Sources
- nexo.com homepage, product navigation and site footer
- nexo.com/en-us homepage, product navigation and site footer, including the Bakkt custody statement and risk disclosures
- The geo-switch prompt shown to US visitors, captured by screenshot
- Nexo Affiliate Program General Terms and Conditions
- All pages read on 11 September 2026
Menus, rates and partners change. We will update this page when they do. Last verified 11 September 2026.
Community discussion
Enjoyed this story? Share your thoughts below.